The Latent Geopolitical Risk of Water Stress as a Climate-Driven Financial and Security Inflection
Water scarcity increasingly threatens not only environmental stability but also national security and financial systems. Despite widespread discourse focusing on temperature rise and carbon emissions, the evolving role of water stress as a systemic risk remains a significantly under-appreciated force with the capacity to reshape capital allocation, regulatory frameworks, and geopolitical alignments over the next two decades.
Emerging regulatory tightening on climate risk, alongside escalating agricultural costs and supply chain vulnerabilities, points toward water stress converging into a critical climate inflection. This development is neither isolated nor transient; rather, it implies a structural disruption with cross-sectoral and cross-boundary consequences. This paper highlights the non-obvious linkage between water stress and financial-national security risk as a pivotal, underrated signal demanding strategic foresight and policy realignment.
Signal Identification
This development qualifies as an emerging inflection indicator due to its increasing observability in regulatory initiatives and financial risk assessments, yet it remains underappreciated in mainstream climate discourse. The UK Prudential Regulation Authority’s (PRA) recent tightening of climate risk governance (with explicit reference to physical risks including water availability) signals rising institutional recognition (Green Central Banking 19/08/2026). Within a 10–20 year horizon, the plausibility of water stress becoming a core systemic threat is high, with sectors like agriculture, insurance, banking, and national security critically exposed.
What Is Changing
Multiple trends converge around water stress as a multi-dimensional climate risk factor. The PRA’s emphasis on embedding climate considerations into core risk frameworks for banks and insurers reflects a regulatory evolution recognizing that climate risks are material at the portfolio and institutional level (Green Central Banking 19/08/2026). This elevates water scarcity from an environmental or agricultural issue to a financial prudential risk, requiring governance attention at the board level.
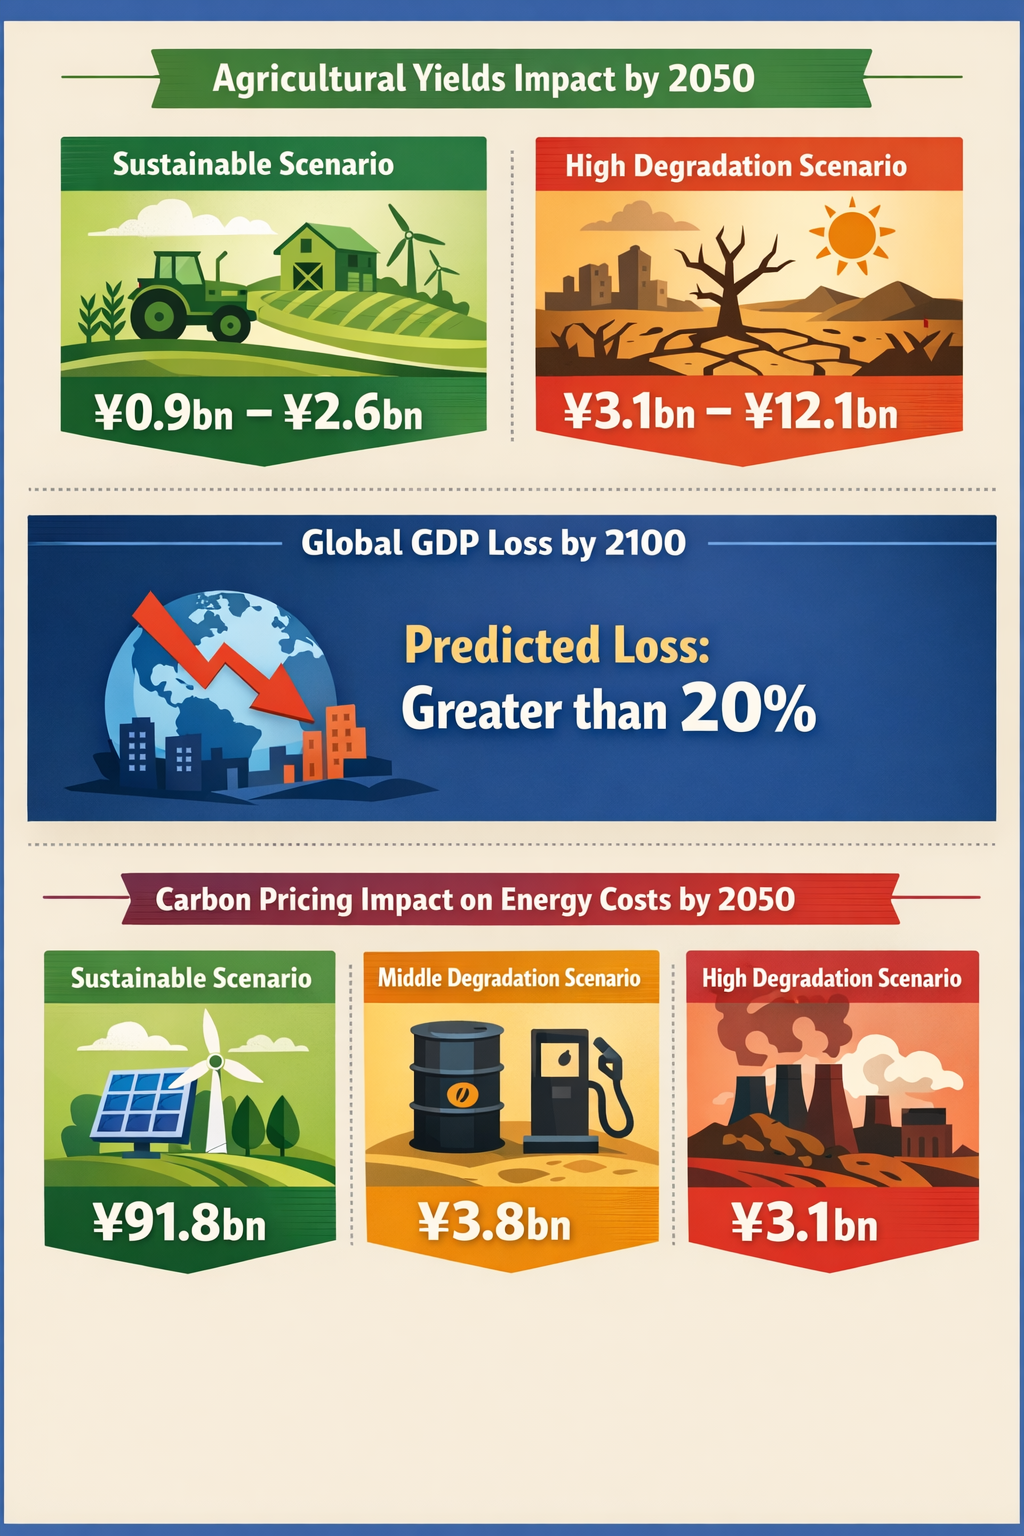
Concurrently, studies warn of agricultural yield declines potentially costing billions by mid-century (¥0.9 bn–¥2.6 bn under sustainable scenarios to ¥3.1 bn–¥12.1 bn under high degradation alongside climate change progression) (Food Navigator 27/08/2026). These losses amplify the linkage between diminishing water availability and economic productivity, underpinning the financial materiality of water stress. Industrial actors, such as the Japanese beverage giant Kirin, also anticipate significant indirect costs, such as carbon pricing inflating packaging expenses by ¥43.8 bn by 2050 under stronger decarbonization trajectories (Food Navigator 28/08/2026), underscoring how water scarcity-driven resource constraints may cascade through supply chains and cost structures.
More broadly, research forecasts global GDP losses exceeding 20% by 2100 owing to climate impacts, embedding water stress as a significant contributor (PMC 14/06/2026). Political risks intermesh with this trajectory, as demonstrated by tensions within the UK Labour party where climate-affected voters and political green agendas pressure fossil fuel drilling debates during periods of extreme weather (The Guardian 08/08/2026).
Thus, water stress emerges not only as an ecological variable but also as a nexus of financial, industrial, and political risks. The under-recognition stems from its indirect manifestation—where water scarcity interplays with sectors and policies traditionally siloed away from climate risk frameworks.
Disruption Pathway
Water stress could evolve from an underestimated physical risk into a dominant systemic threat through a series of compounding mechanisms. Increasingly frequent and severe droughts will degrade agricultural yields and industrial water-dependent production, escalating commodity price volatility and supply chain instability. This will drive investment reallocation toward water-resilient assets and technologies, fundamentally shifting capital flows.
Financial institutions, observing escalating losses and regulatory pressure from entities like the UK’s Prudential Regulation Authority, may escalate risk premiums or restrict exposure to water-dependent sectors. This dynamic could constrict credit availability for traditional agribusinesses and water-intensive industries, pressuring corporate behaviour toward water efficiency and innovation.
At the same time, national governments will confront heightened social stress from resource scarcity, potentially provoking water-related conflicts and migration. Strategic national security frameworks will integrate water scarcity as a core vulnerability, potentially revising defence priorities and international cooperation structures. Such shifts may fracture or realign global trade and diplomatic relations.
These cascading effects could compel industrial redesigns—shifting away from water-heavy processes, accelerating deployment of water reuse technologies and biobased alternatives, as suggested by Kirin's investment in green packaging and recovery strategies (Food Navigator 28/08/2026)—and promote circular economy models to reduce dependency on limited freshwater supplies.
Feedback loops include rising energy demand for water treatment and transport, potentially aggravating carbon emissions unless coupled with clean energy transition efforts. Regulatory regimes may tighten mid- and long-term oversight of water-related climate risks, possibly integrating water metrics into financial disclosure and risk management standards. This convergence may precipitate paradigm shifts where water sustainability underpins financial viability and national security doctrine.
Why This Matters
For senior decision-makers, neglecting water stress’s latent systemic risk could result in misallocated capital, underpriced financial risk, and unanticipated political instability. Capital allocation decisions may face increased volatility and regulatory compliance risks as climate-aligned governance frameworks enforce water risk integration at scales not yet standard. Insurance and banking sectors stand to incur meaningful losses if water-related risks materially escape risk models that underestimate hydrological variability.
Industrial actors may confront escalating operational costs, supply disruptions, and reputational risks, necessitating adaptation investments or strategic repositioning. Regulatory bodies must anticipate a shift toward prescriptive rules linking water risk mitigation to climate policy and financial system resilience. Governance structures will likely require enhanced coordination across environmental, economic, and security domains to navigate this emerging compound threat.
Implications
The growing recognition of water stress as a systemic threat could plausibly trigger structural change rather than mere cyclical perturbations. Financial institutions might reprice water-dependent assets decisively, accelerating capital flows into water-resilient innovations and geographies. Regulatory frameworks may incorporate water risk as a core factor alongside carbon, embedding it into prudential requirements and disclosure obligations.
This development should not be mistaken for incremental environmental policy shifts focused solely on emissions. Instead, it represents a multi-sectoral, interdisciplinary inflection likely to reshape governance and investment paradigms. Competing interpretations may argue water remains a localized or regional issue lacking systemic breadth; however, increasing interdependencies between water, economy, and security underline a high plausibility for expansive impact.
Early Indicators to Monitor
- Expansion of climate risk regulatory requirements explicitly including water stress from central banks and financial regulators
- Increases in water-related insurance claims and underwriting restrictions
- Venture capital and corporate R&D clustering around water-efficiency and circular economy technologies
- Capital reallocation patterns favoring water-scarce regions or industries investing in water resilience
- Geopolitical discourse and national security policies integrating water scarcity as a threat multiplier
Disconfirming Signals
- Significant breakthroughs in global freshwater supply technologies easing water scarcity
- Regulatory rollback or deprioritization of water-related risk within climate finance frameworks
- Successful international water-sharing agreements reducing transboundary conflict risks
- Economic decoupling from water-intensive sectors via alternative materials and circular economy transitions at scale
Strategic Questions
- How should capital allocation frameworks evolve to integrate water stress as a material climate risk across sectors?
- What governance mechanisms can effectively coordinate climate, financial, and national security policies to mitigate systemic risks from water scarcity?
Keywords
Water Stress; Climate Risk Management; Financial Regulation; National Security; Agricultural Yields; Capital Allocation; Supply Chain Resilience; Regulatory Frameworks
Bibliography
- Last year, the UK Prudential Regulation Authority tightened climate risk management rules for UK banks and insurers, requiring them to embed climate considerations into core risk frameworks and board-level decision making. Green Central Banking. Published 19/08/2026.
- Declining agricultural yields could have a financial impact of ¥0.9 bn–¥2.6bn by 2050 under the Sustainable Scenario, rising to ¥3.1 bn–¥12.1bn under the High Degradation & Climate Change Progression Scenario. Food Navigator. Published 27/08/2026.
- The Japanese beverage giant’s latest climate-risk assessment estimates that carbon pricing could add ¥43.8bn to packaging costs by 2050 under its Sustainable Scenario, which assumes a stronger global shift towards a low-carbon economy. Food Navigator. Published 28/08/2026.
- As a result of the impacts of climate change in Australia and across the world, the social and economic impacts will be substantial, with global gross domestic product losses predicted to be greater than 20% by 2100. PMC. Published 14/06/2026.
- Many Labour MPs are worried that support for expanded drilling will alarm voters enduring a summer of extreme weather supercharged by the burning of fossil fuels - especially with a resurgent Green party attracting new support. The Guardian. Published 08/08/2026.